Originally published on LinkedIn, October 9, 2026
You’re only as good as your last game. This is as true for companies as for people. Standing still takes effort, getting ahead takes growth. (See Rassie and the Boks #bokbefok)
Which is why McKinsey & Company’s Three Horizons of Growth is my favourite framework. It is bloody simple too: a C-suite can perform a “no-BS” self-assessment in an hour. Horizon 1 (H1) defends and extends the core that makes todays profit. Horizon 2 (H2) builds emerging businesses next to the core. Horizon 3 (H3) seeds options that may pay off years out.
Growth leaders have 2 additional commonalities.
First, growth is not an end in itself, “growth for the sake of growth is the ideology of the cancer cell” (Edward Abbey). Investment discipline is non-negotiable. Second, integrated, flexible technology platforms are needed to carry growth. With AI compressing timelines, this requirement becomes even more important.
The chart below is my summary view of where SA banks stand. Others will see it differently. Every C-suite should draw its own.
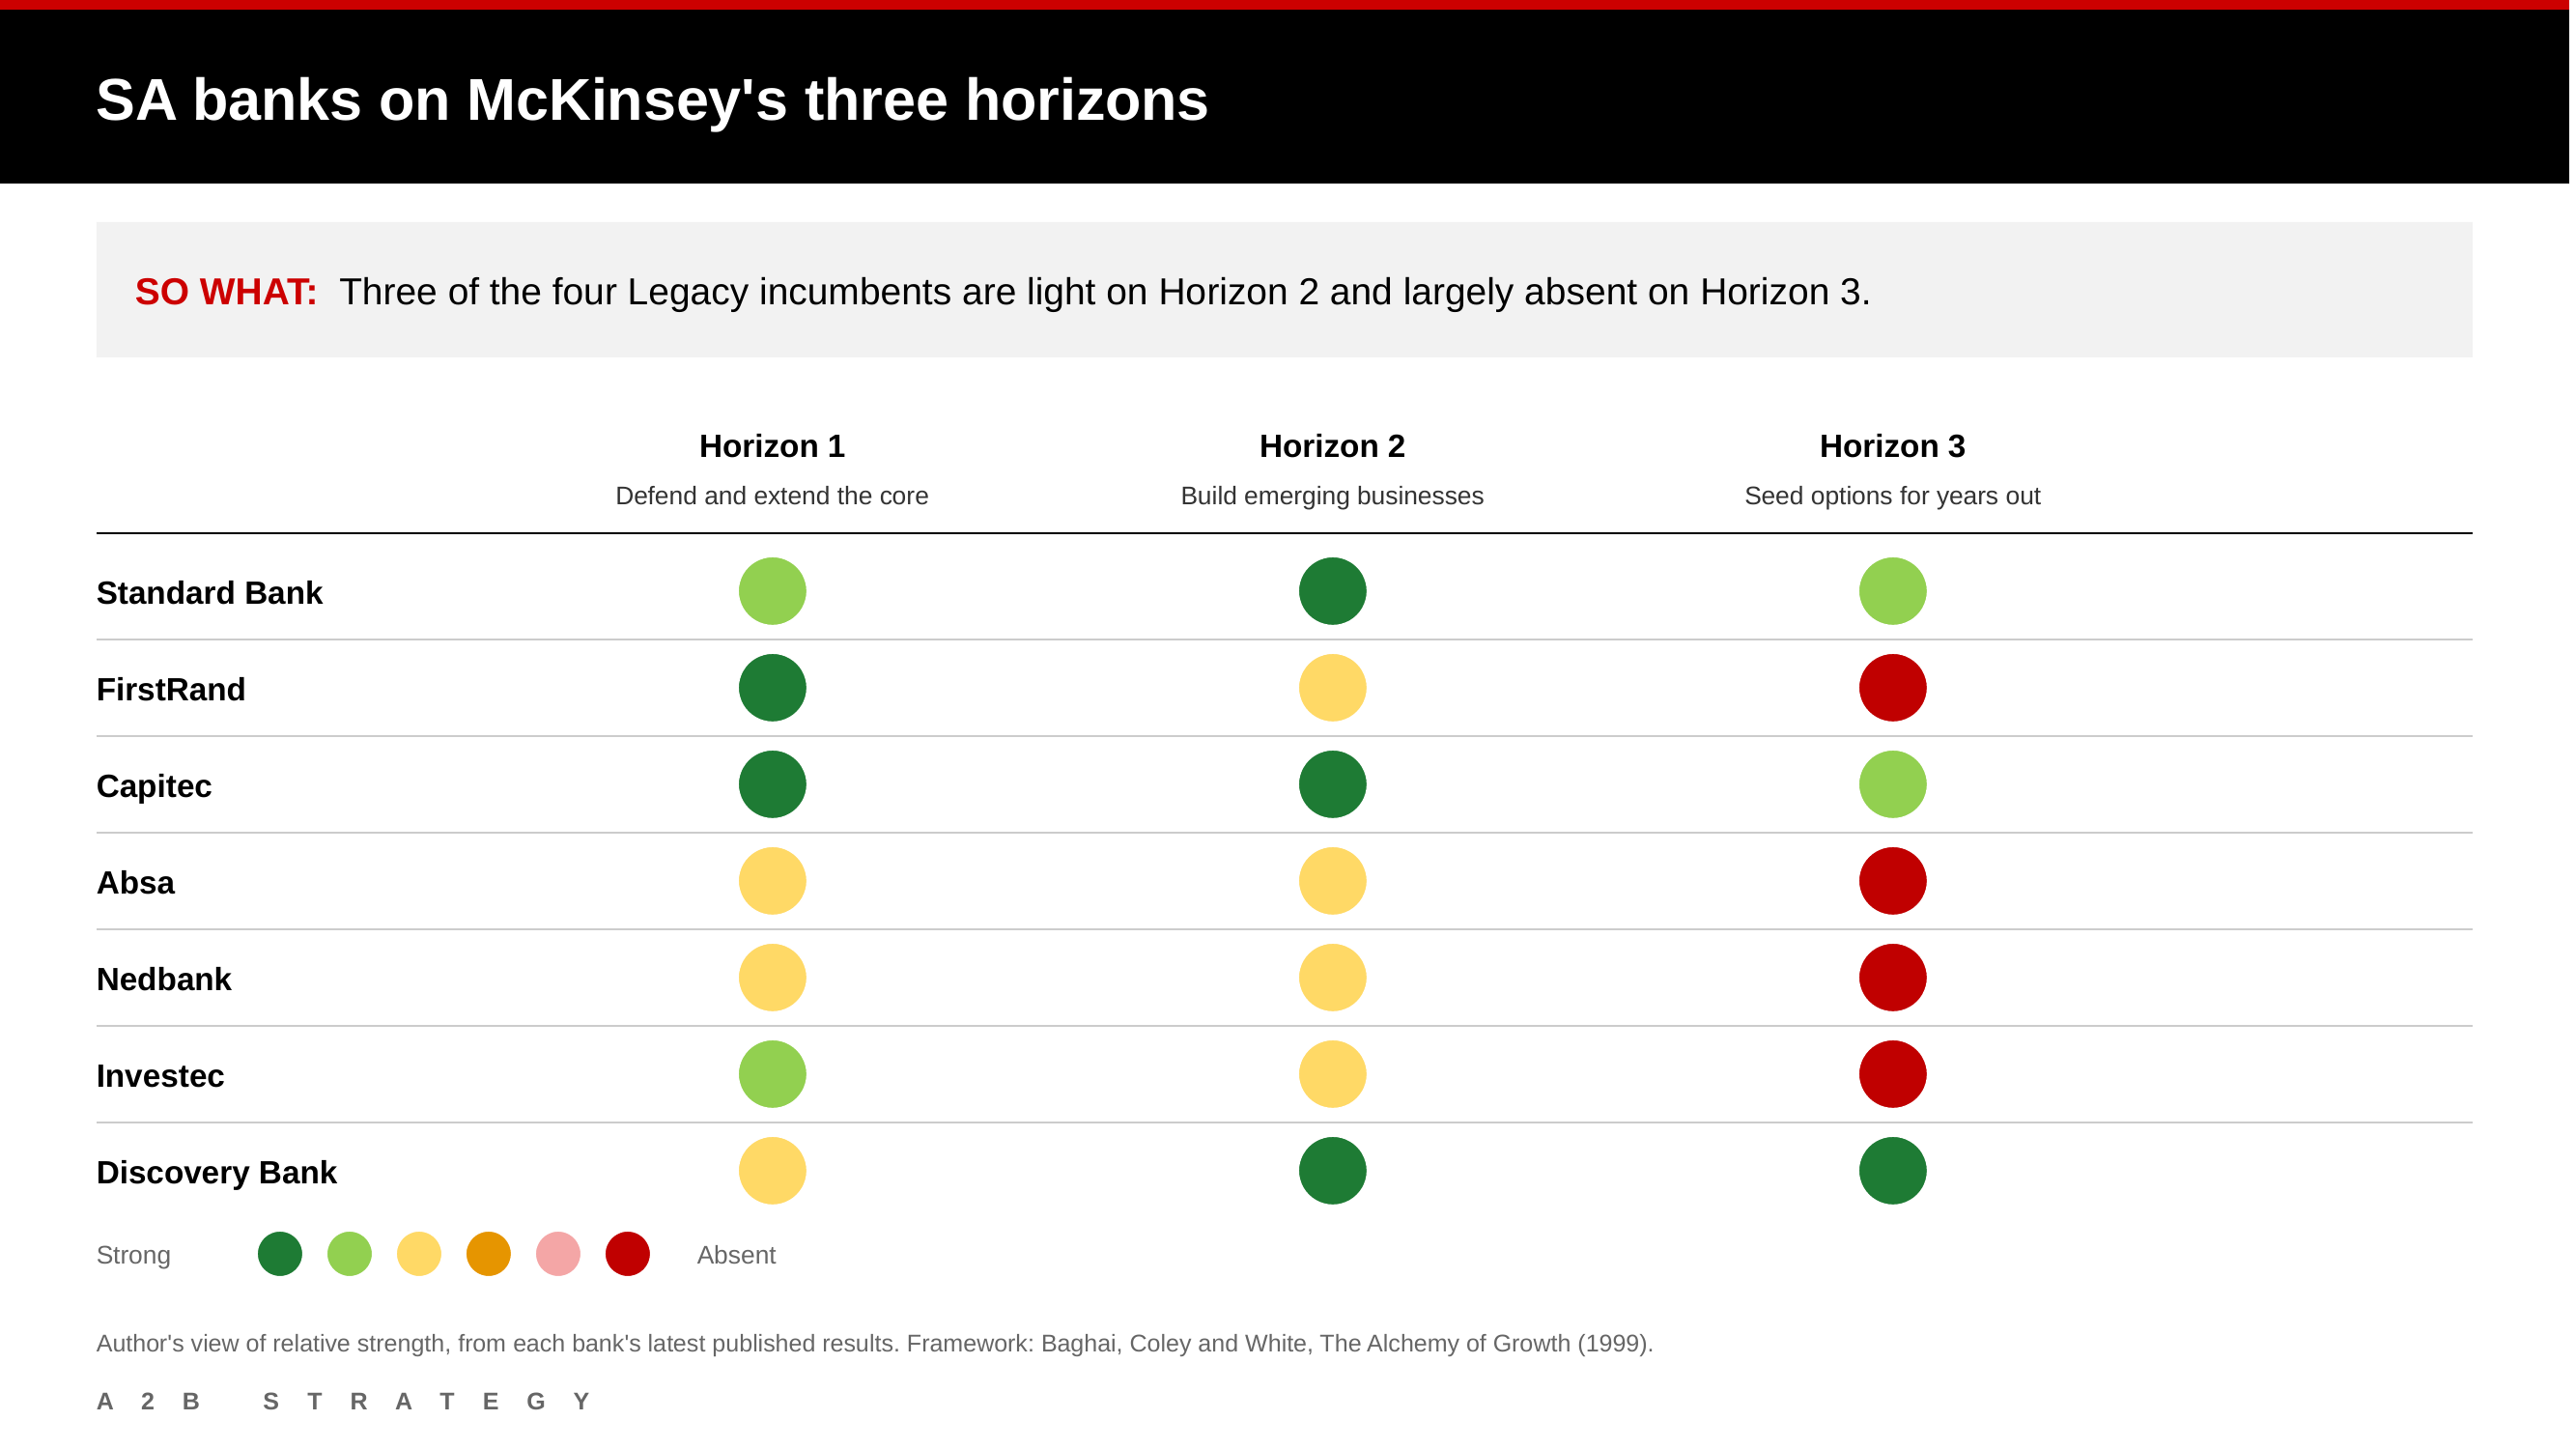
Capitec ticks all three horizons better than any of the Legacy 4 incumbents. Unsurprisingly, they showed their own four-horizon version in their last two results presentations. The “religious” fervour of their client-centricity is matched by their looking to the future.
FirstRand leads H1 and has for years. Optasia aside though, H2 and H3 look spartan.
Absa Group and Nedbank have aggressively addressed H1 and H2. The numbers have not turned yet, but both have given themselves a chance to thrive, not just survive.
Standard Bank Group’s build-out of market-making, investment banking and the platforms beneath them on an African portfolio double the size of competitors is both a moat and growth flywheel that will sustain them across all three horizons.
Investec has been very decent in its H1 niches and has lately woken up to H2.
If I could own only one South African share for ten years, it would be Discovery Limited. This is not just a banking call: it has the smartest people, is far ahead on AI, has the richest data set, low-cost digital distribution, “shared-value” incentivisation, and revenue-generating H2 and H3 options across several industries and 6 continents.
For “laggards”, the last-game rule also offers hope. Growth gaps are easier to plug than ever. Two means exist, first there’s AI: days before a bank launched a financial advice tool that was over five years in the making, I watched an elite AI-engineer build something better. In five days! Speed-to-market can be transformed. Second, acquisition: SA has scores of properly decent fintechs with the talent, speed and innovation the big institutions lack, but not the distribution or funding. A smorgasbord to compensate for corporate inertia.
Planning a strategy session? For a dispassionate read of the landscape, or a neutral facilitator in the room, mail brad@a2bstrategy.co.za


Leave a Reply