Originally published on LinkedIn, October 6, 2026
I love old leather-bound books and surprise vinyl finds in dusty charity shops. Maybe it comes with being a ballie. In this vein I have dusted off some old strategy maps and laid them over new territory: the SA banks. First up, BCG’s 1970 growth-share matrix, built for one conglomerate, bastardised here for the Big 5 (chart below).
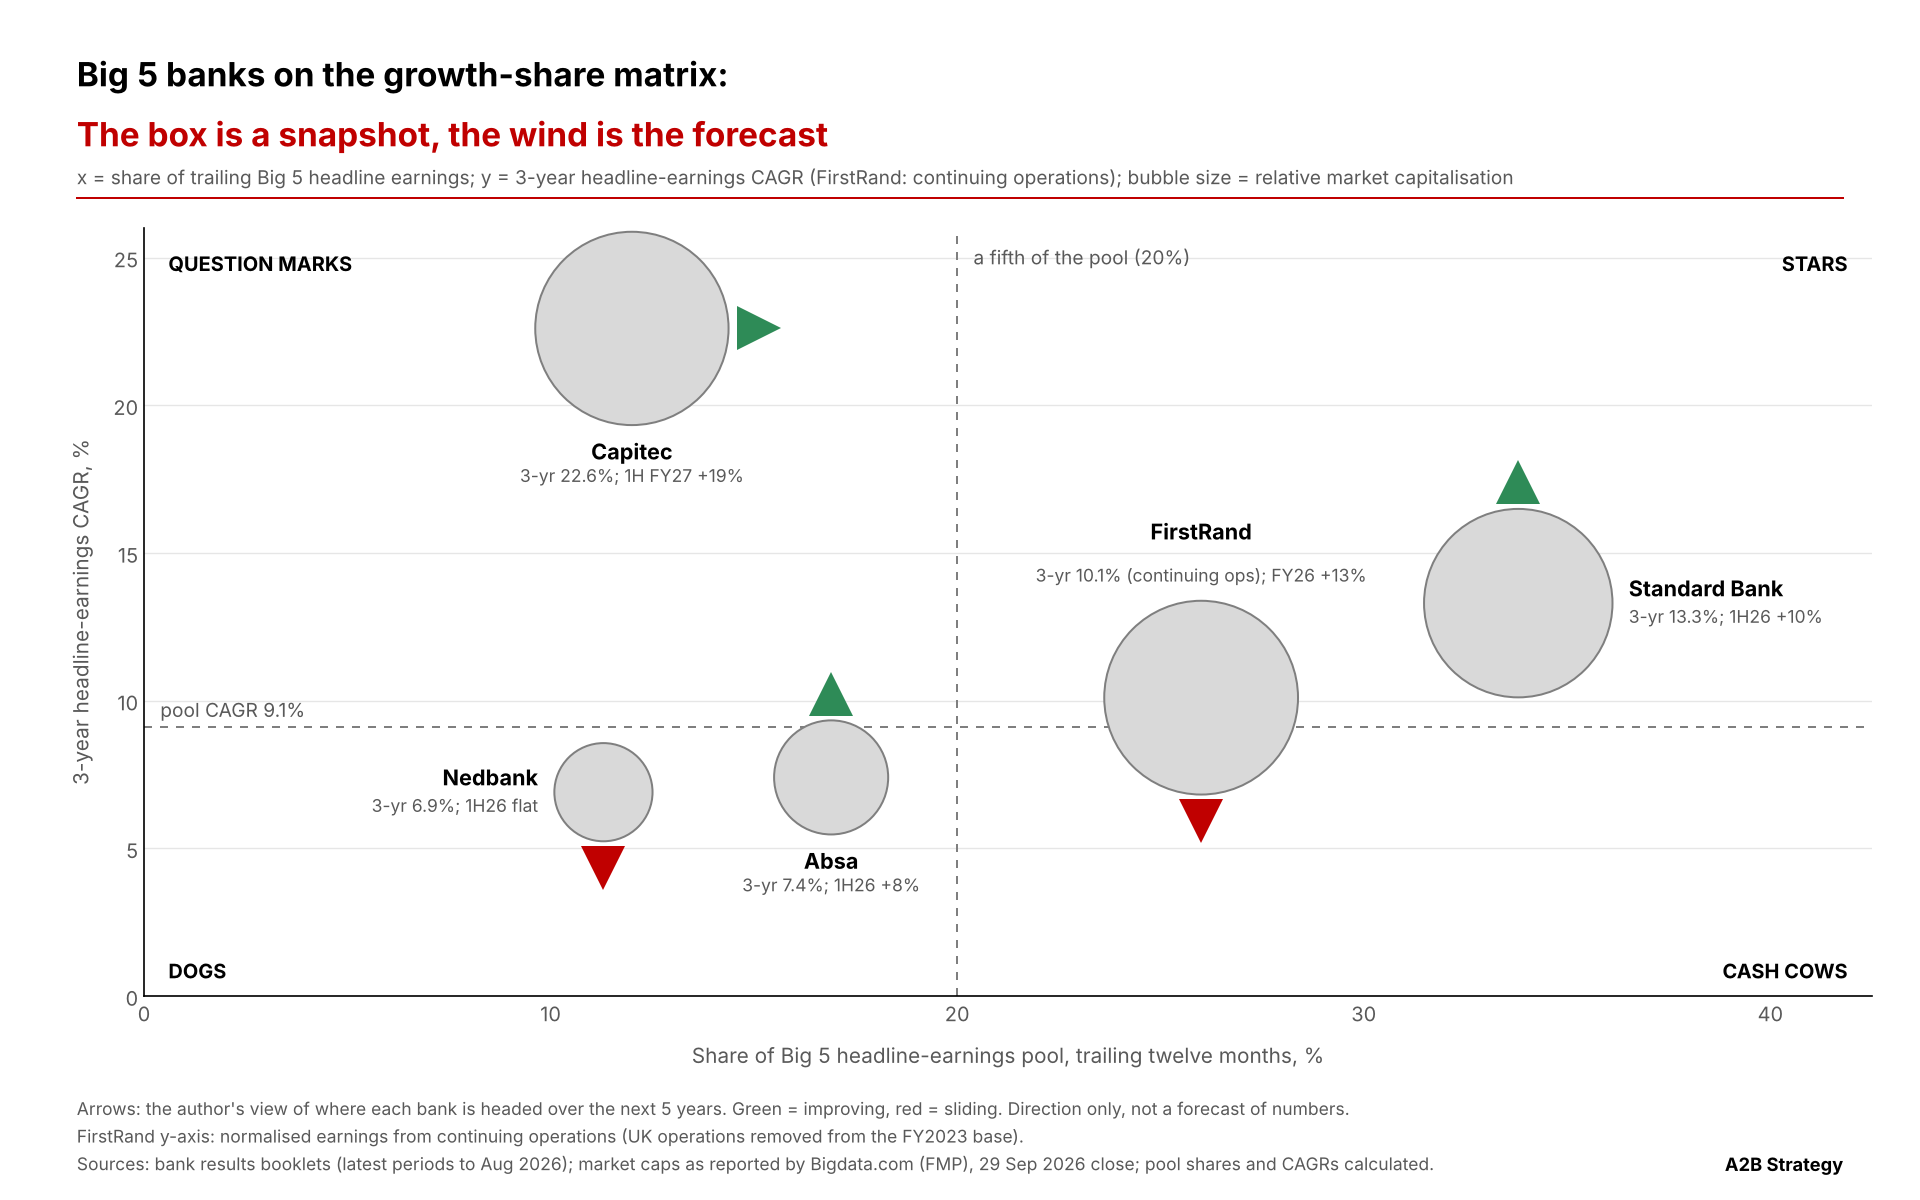
The so-what: the box is a snapshot, the wind is the forecast. Watch the head- and tailwinds on each bank, not the label.
Absa Group and Nedbank sit in the “dog” box. That is unkind to two new-broom CEOs moving at real speed, so read the label as a starting point, not a verdict. After my last Absa post an industry luminary sent me this pearl: “Retail banking is won inches at a time, investment banking in the odd mile. It will take Absa 15 years to rebuild retail”. If CIB delivers, Absa moves to question mark. If SA business does not turn, the box does not change. Nedbank has decluttered well, but being subscale in SA retail and business banking is a sharper headwind. A tough ask.
Capitec is technically a “question mark”: a fraction of the earnings of Standard Bank Group and FirstRand, but growing faster and valued the same. The market doesn’t give a continental. It is the only big bank that gives no earnings guidance (more walk, less talk) and ten years of headline earnings growth at 18% a year is extraordinary. Plus, at least 5 white-space growth vectors remain untapped. The new test is on home turf: GoTyme Bank with Sanlam behind it, and Pep’s plusb, both with lower cost bases, both likely to be recapitalised if they stumble. Capitec has never faced a lower cost competitor before.
Standard Bank is a “star”, no asterisk. The 2027 CEO and CFO handover is being stage-managed to perfection, and the CIB network effect across Africa is a beast. Sim’s talk of industry consolidation does not suggest a passive observer. The only headwind is Absa hitting its weak spots. For now, not material.
FirstRand is a “star” radiating “cash cow” vibes. Salary increases at less than inflation sit next to a dividend increase 4x CPI. Does guidance towards a 45% cost-to-income ratio come from topline outperformance? What are the growth vectors? Opening the credit taps (Optasia, looser origination) will deliver in a falling-rate, growing economy. Absa tried that four years ago and it did not end well. A new venture in Africa? The track record over 20 years is not compelling. RMB restructuring? Bold to expect a step change. The day Private- and Business Banking stop overdelivering, the picture becomes murky. Low double-digit earnings guidance will doubtless be met! Costs will be cut, which means headcount. But shrinking yourself to greatness is not the strategy of a star.
Next: three horizons, and why 70:20:10 is dead.
If you are planning a strategy session and want a dispassionate read of the competitive landscape, or a neutral facilitator in the room, mail brad@a2bstrategy.co.za


Leave a Reply